F Piero Alexander | Quantitative Economist
CV About Experience Projects Skills Contact
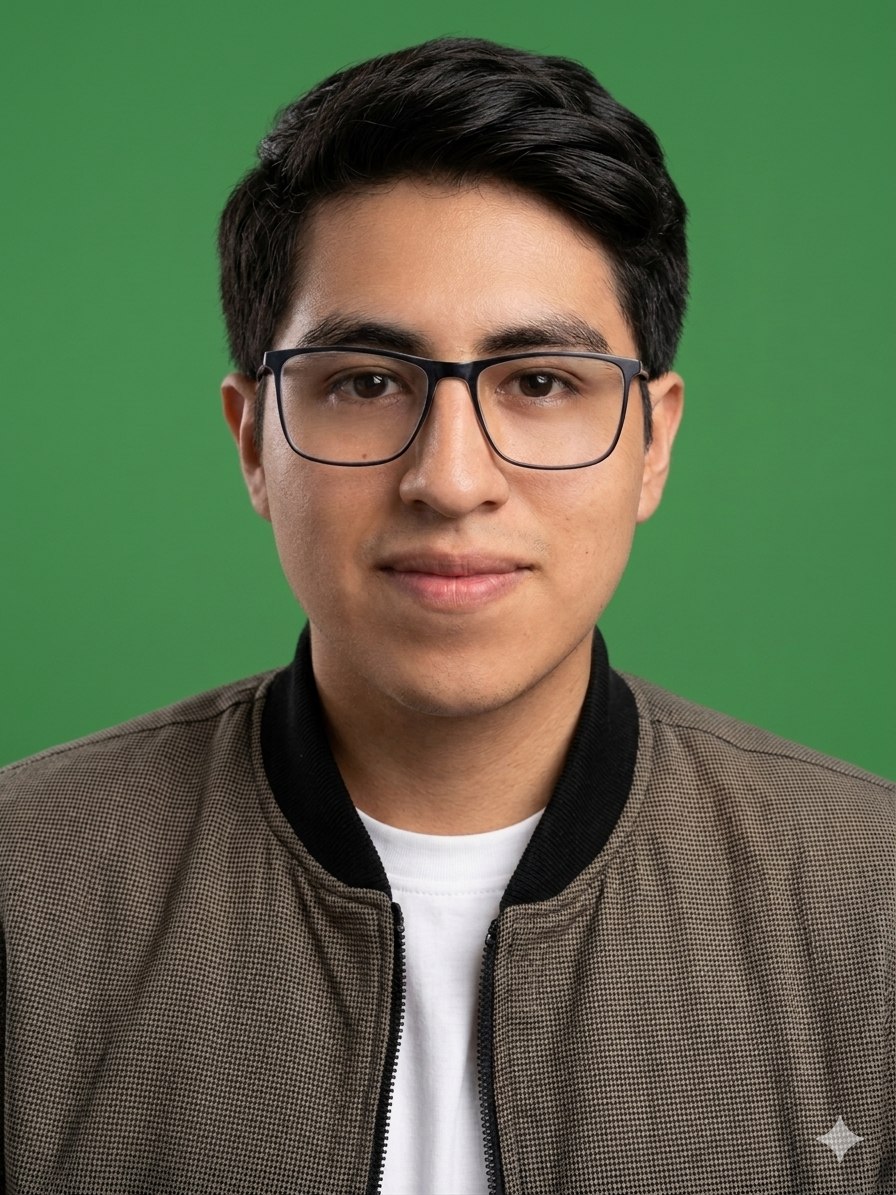
Piero Alexander Simeon Bustillos

Piero Alexander Simeon Bustillos

Quantitative Economist

Current Experience:

Research & Econometrics

UNMSM · IAE-CSIC

Quantitative Models

Specialization:

• Bayesian Econometrics
• VAR/SVAR Models
• Macroeconomic Analysis

Kaggle Email 968 639 675

Piero Alexander
Simeon Bustillos

Quantitative Economist · UNMSM · IAE-CSIC

I transform complex data into actionable insights using advanced mathematical models, Bayesian econometrics, and scientific programming. Specialized in VAR/SVAR models and macroeconomic analysis.

Languages & Tools:
Python MATLAB R Stata EViews VAR/SVAR Scikit-learn BVAR Econometría
4
Languages (Python, R, MATLAB, Stata)
3+
GitHub Projects
10k+
Monte Carlo Simulations
ANALYSIS
Winter School 2025 RIEF
Track Record

Experience

Development, automation, and data processing in professional environments.

March 2026 — Present

Preprofessional Intern

Macroconsult

Development of web scraping solutions for real-time data extraction. Design and implementation of automated ETL workflows for data processing and transformation. Creation of scalable data pipelines and maintenance of continuous collection systems.

2026 — Present

Research Assistant

Renato Vassallo, PhD

Estimation of BVAR models with Pandemic Priors, MS-BVAR, Panel BVAR and threshold BVAR in MATLAB. Identification of macroeconomic regimes and calculation of structural impulse-response functions (IRFs).

2025

RIEF Winter School Scholar

Advanced International Program

Specialization in quantitative macroeconomics and finance: market dynamics, asset management, financial risk and applied structural modeling.

Portfolio

Featured Projects

Tools and quantitative models built from scratch.

VarPy

Python VAR / SVAR Econometrics APIs

Complete pipeline for VAR/SVAR models with sign restrictions. Direct connection to BCRP and World Bank APIs. Includes: stationarity tests (ADF, PP, KPSS), automatic VAR estimation, structural SVAR identification, impulse-response functions, variance decomposition (FEVD), complete diagnostics and forecasts with bootstrap confidence bands. Fully modularized and documented.

View on GitHub

Macroeconomic Extractor

Python Yahoo Finance World Bank Demo

Tool for extraction and analysis of macroeconomic data and asset prices. Integrates World Bank and Yahoo Finance data for automatic analysis. Enables extraction of time series, interactive visualizations and calculation of macroeconomic indicators seamlessly. Demo phase in continuous development.

View Project

BCRP Macroeconomic Analysis

MATLAB MS-BVAR Bayesian BCRP

Estimation of BVAR models with Pandemic Priors and MS-BVAR in MATLAB. Analysis of macroeconomic dynamics: BCRP Reference Rate, Business Expectations, GDP Growth and Terms of Trade. Structural IRFs and macroeconomic regime analysis.

View Analysis
Technical Stack

Key Competencies

Tools and methodologies I use daily in research and analysis.

HTML
Basic
CSS
Basic
JavaScript
Basic
MATLAB
Advanced
Stata
Advanced
EViews
EViews
Advanced
Python
Advanced
R
Intermediate
Scikit-learn
Intermediate
Pandas & NumPy
Advanced
VAR / SVAR
Specialty
Monte Carlo
Advanced
Econometrics
Specialty
Mathematics
Specialty
Contact

Let's collaborate on quantitative research

Available for econometric modeling projects, macroeconomic analysis, and academic research matters.